The Ten Minutes Before the Opening Bell
It's a little after 8 a.m. and the train is packed. One hand grips the rail; the other thumbs open your brokerage app to see how the market closed. Your balance is up a bit, and you quietly do the math: at this pace, how many more years until you don't have to squeeze onto this train every morning?
If you're someone who works a job and invests on a schedule, that thought probably sounds familiar. Your paycheck lands, rent and bills and groceries come out, and whatever's left goes into the market in small, steady amounts. Then you tell yourself: just a few more years. The trouble is, however you run the numbers, "a few more years" always seems to stay far away.
So one content creator ran an experiment. He put the same question to seven AIs: ChatGPT, Claude, Gemini, Grok, Perplexity, DeepSeek and Copilot. He didn't ask "How do I retire early?" He asked something more practical: how can an ordinary employee gradually depend less on a paycheck, and stop relying only on selling their time for money?
Seven AIs, built by different companies and trained on different data. You'd expect seven different answers. Instead, to his surprise, they pointed in almost the same direction. And the first step may be the opposite of what you'd expect.
The First Answer: Don't Quit Yet
For anyone itching to leave the office, the instinct is usually to quit and go all in on their own thing. But the first answer from nearly all seven AIs was the same: don't rush to quit.
A steady paycheck ties up your time, but it also gives you something precious: reliable cash flow. As long as your salary keeps coming in, your new venture doesn't have to support your whole household right away, and you're far less likely to make a decision you regret just because next month's rent is due.
Look at it another way. Your job doesn't have to be the obstacle. It can be the "angel investor" behind your second income. Each month, part of your paycheck covers living costs, part goes into an emergency fund, and the time and resources left over go toward learning a skill, finding clients and slowly building something of your own.
The point isn't to stay in that job forever. It's to let the job handle stability for now, until the other path has grown strong enough to stand on.
Investing Alone Can Take a Long Time
Investing matters, of course. Several of the AIs described the same basic routine: keep spending in check, put a fixed amount into diversified index funds every month and let your assets compound. That's the dollar-cost averaging (DCA) many working people already do. You don't try to guess highs and lows; when the date comes, you invest, and you hand your discipline to a system instead of to your mood that day. (For how DCA stacks up against trying to buy the dip, see this comparison.)
The catch is that however disciplined your DCA plan is, the money going in still comes from your paycheck. If your income is modest, the amount you can invest each month is limited, and even with perfect discipline it can take many years to build enough to live on.
Some of the AIs ran the numbers. Claude used the example of saving a quarter of your income and estimated it would take roughly 30 years to reach financial independence. Grok pointed out that pushing your savings rate to half could cut that to 15 to 18 years. These are estimates under specific assumptions; real results depend on your income, spending, investment returns and the kind of life you want.
Whether those numbers are precise isn't the point. What they reveal is: saving more matters, but earning more can change the speed of the whole plan. If your income never grows, there's always a ceiling on what you can invest. So instead of only asking how to squeeze a bit more out of your current salary, it's worth asking a second question: can you open up another stream of income and put the extra into assets?
Why Did Seven AIs Point to the Same Path?
Six of the seven AIs stressed the same route: learn a skill the market will pay for, sell it as a service to businesses first, then grow that service step by step into a business of your own.
These skills don't require an expensive degree or years of training. AI automation, email marketing, copywriting, search engine optimization, web development, data analysis, bookkeeping and customer relationship management could all be starting points. The key isn't chasing whatever skill is hottest. It's finding a problem businesses actually have, that you're able to solve, and that someone is willing to pay to fix.
Why focus on business clients? Do the math. Say you sell a $20 product to consumers and want $5,000 a month in revenue. You'd need to sell 250 of them. But if a business will pay you $1,000 a month to solve a problem that's giving it headaches, you only need five clients to reach the same revenue.
That doesn't mean business clients are easier to land, and revenue isn't profit. But for an individual with limited resources, solving a truly valuable problem for a handful of clients is an easier place to start testing an idea than trying to serve thousands of consumers from day one.
The one that stood apart was DeepSeek. It leaned toward the traditional financial-independence playbook: push for raises, keep a high savings rate and invest for the long term, with side hustles and freelancing mentioned along the way. Even so, whatever each AI emphasized, the same three threads ran through every answer: earn more, spend less and turn money into assets.
A Skill Isn't Enough. You Have to Sell It
Learning a skill doesn't mean income will start showing up on its own.
The creator behind the experiment learned this the hard way. He once tried to sell an online course on growing a YouTube channel, and discovered that knowing a lot isn't the same as convincing people to pay.
This is the part many people overlook. They pour time into courses, certifications and researching tools, but never actually go out and find a customer. The market doesn't pay you for working hard. Customers pay because they believe you can solve their problem.
So rather than preparing behind closed doors for a whole year, go find your first paying client early. You may get turned down. You may discover that a service you thought was valuable is something nobody wants. But that feedback is often worth more than one more course.
Year One to Year Five: From Selling Time to Building a System
The path can be broken into a few stages.
Year one: lay the foundation. Keep your job, control your spending, build an emergency fund, then choose one skill and set aside 10 to 15 hours a week to practice and look for clients. Aim to earn your first dollar as early as you can. Even if, by year-end, it only adds $500 a month, you've proven something important: people are willing to pay for what you can do.
Year two: turn gigs into packages. Once your skills are sharper and you understand what clients want, you can raise your prices and shape your work into clearly defined packages instead of billing by the hour forever. For example, instead of charging hourly to "help with marketing," offer a package that "sets up an automated email sequence within 30 days," with the deliverables and the price spelled out. The smoother your process, the more you earn for the same time.
Years three to five: don't let the side business become another job with no off switch. Write down your repeatable processes, hand them to automation tools or AI, or bring in help. You can also turn a mature service into software, a subscription product or a digital product.
This step is the critical one. If all your income still depends on how many hours you work each day, earning more doesn't necessarily make you freer. What you really need to build is a system that keeps running without you handling every task yourself.
So When Should You Actually Quit?
On the timing of quitting, the seven AIs were far less united.
Gemini was the most aggressive: once your business income has hit about three-quarters of your salary for three months in a row, and you've saved 9 to 12 months of living expenses, you can start considering a move. The others were more cautious. Some wanted business income to cover all your living costs reliably first; others said you should build up enough invested assets so you're not relying on a single income stream.
The creator's own approach is worth noting. His business income already exceeds his salary, yet he still set himself a bar: save $100,000 as a cushion before he even considers leaving.
Earning more than your salary doesn't mean you're ready to take on every risk.
Clients can leave, markets can shift, and revenue can drop sharply without warning. Before quitting, the question isn't just how much you're earning now. It's how stable that income is, how long your cash can carry you, and whether you can live with the uncertainty. Quitting shouldn't be an exciting goal in itself. It should be the natural next step once your replacement income, your financial cushion and your tolerance for risk are all in place.
The Most Dangerous Trap Might Be a Raise
Building a second income is hard enough. But there's a quieter trap: when income goes up, spending tends to follow.
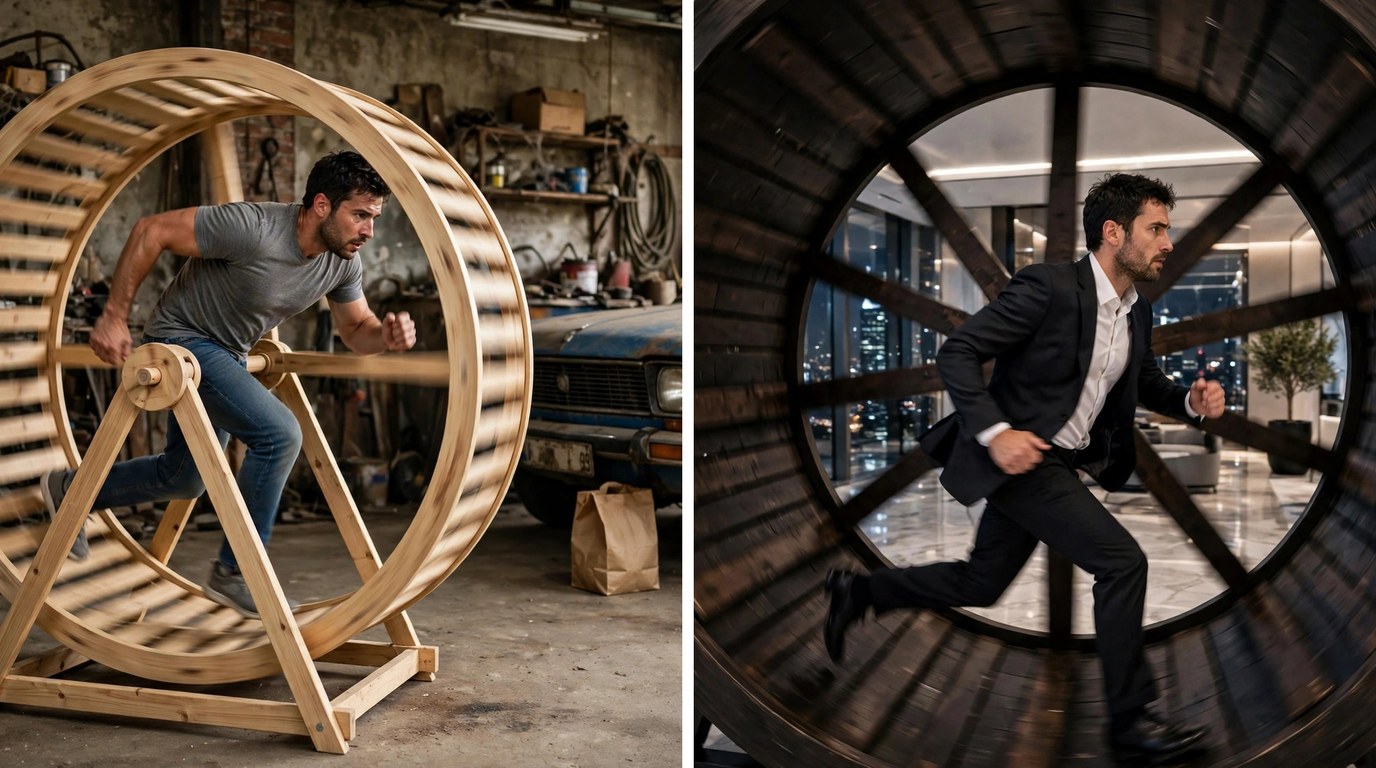
After a raise, you get a nicer car, move into a bigger place, eat out a little more often, and the extra money is quickly swallowed by a new cost of living. You look like you're earning more, but you're no closer to freedom. You've just traded the hamster wheel in the garage for one in a penthouse.
If your spending rises every time your income does, it's hard to save enough capital and hard to truly reduce your dependence on a job. That's why this path isn't only about earning more. It also means keeping your cost of living in check, investing consistently and turning extra income into assets that create value over the long run.
Earn it, keep it, invest it. All three have to happen together. Drop any one, and even a thriving business may just swap your dependence on a paycheck for a different kind of busy.
The Real Exit: No Longer Living Only by Selling Your Time
Ask seven AIs, and you don't get a magic shortcut.
None of them promised that buying the right asset, learning the right skill or starting a company would guarantee an escape from the 9-to-5. Most of their answers were refreshingly practical: keep your current income, raise your value in the market, learn to sell, build a business step by step, control your spending and put the surplus into long-term assets.
This path may take years, with failures and detours along the way. It isn't saying everyone should become an entrepreneur, and it certainly isn't saying there's anything wrong with having a job. The real difference is this: does your life depend on a single source of income forever? Do you have to wait for the next paycheck every month just to keep living the life you have now?
Financial independence and building wealth aren't quite the same thing, either. Investing helps you build capital, while a business, a piece of software, a body of work or any other system that keeps producing income can give you different options. The two can work together; you don't have to pick one.
In the end, all seven AIs came back to the same idea: you don't need to rush out of the life you have now. Start from where you are and build another possibility, one step at a time. The goal isn't simply to stop working. It's to stop depending only on selling your time to get by.
This article is based on a creator's experiment putting the same question to seven AIs: ChatGPT, Claude, Gemini, Grok, Perplexity, DeepSeek and Copilot. Figures such as years to financial independence and income thresholds are each AI's estimates under specific assumptions, not guaranteed outcomes. This article is educational and does not constitute investment advice.