After a long run-up, investors get stuck in the same bind every time: the position you're holding has already climbed a lot, so chasing it further feels uneasy — but once the market actually turns down, it never feels like the right moment to buy either. Everyone knows a rally like this can't run forever, but nobody knows exactly when it turns. So "I'll buy once it comes down" sounds perfectly rational, until you actually try to do it. The moment prices start falling, a lower price rarely feels safe — instead, you wait for it to fall a little further, and then a little further than that. And that's the trap: by the time everyone finally agrees "this must be the bottom," the market has usually already turned back up.
In 1997, Lynch said something that sounded strange
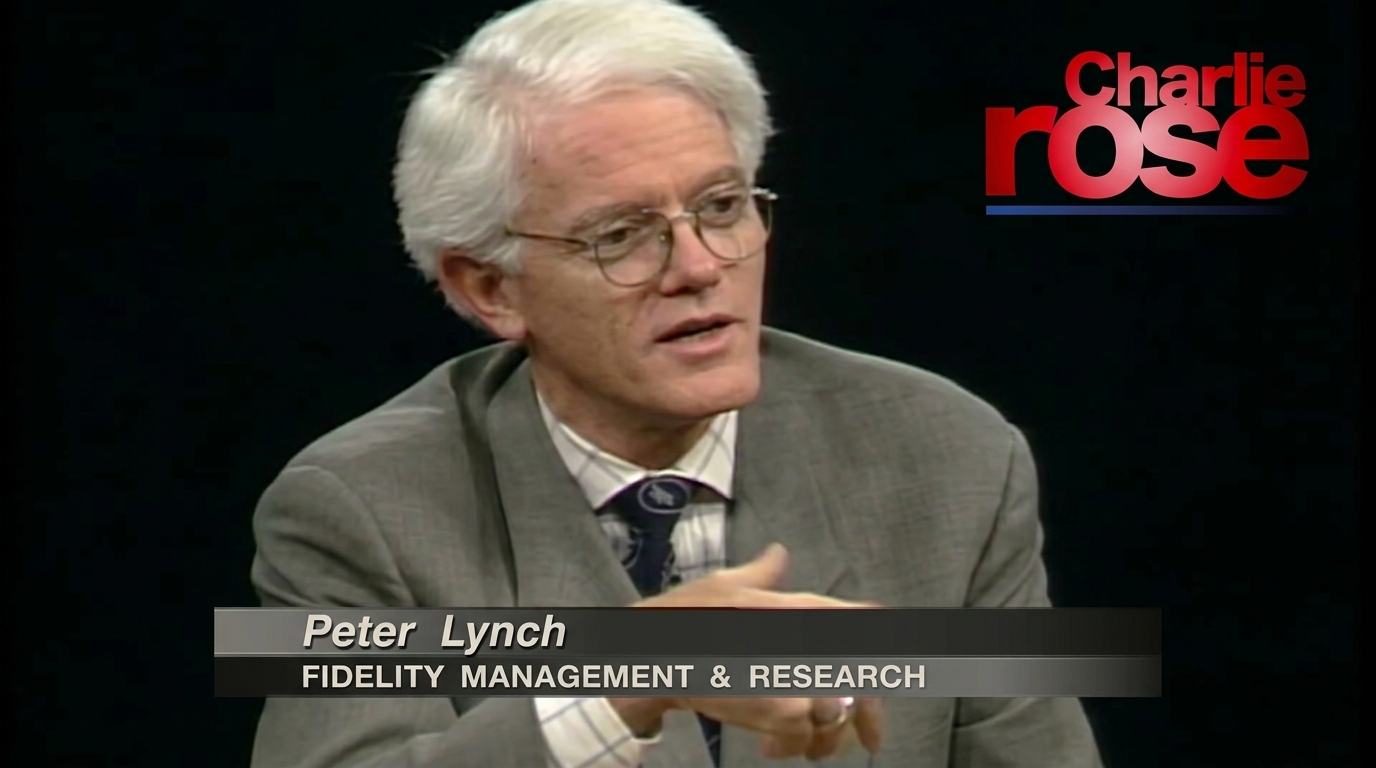
None of this is new. In 1997, Peter Lynch sat down with Charlie Rose while the U.S. market was sitting at an uncomfortably high level of its own. The Dow had run from roughly 4,000 to about 8,300 over about two and a half years, valuations were drawing real scrutiny, and the Asian financial crisis had just hit, sending markets into sharp swings. That's the backdrop for the line Lynch became known for: "I'd rather it plunge 1,000 points than keep climbing all the way to 12,000." On its face, that sounds bizarre — why would a lifelong stock investor want the market to fall? But Lynch wasn't worried about the drop itself. He was worried that if the market kept climbing fast, prices would get ahead of years of future earnings, until everything simply cost too much.
"I'd rather it plunge 1,000 points than keep climbing all the way to 12,000."
Lynch was pointing at something more fundamental: a stock's price eventually has to answer to the company's actual earning power. Sentiment, liquidity, and expectations can drive the market in the short run, but once valuations get so high they can only be justified by years of fast growth still to come, every further rally makes investing riskier, not safer. A real correction is uncomfortable, but it's also what drags overpriced stocks back down to earth. Lynch even compared a correction to "castor oil" — unpleasant to go through, but not necessarily bad for the market's long-term health.
What to actually do once prices fall
For most investors, the part that matters isn't the drop itself — it's what you do next. Lynch didn't buy just because a stock had fallen hard. He went back and re-checked the company first: Has anything about the fundamentals changed? Is debt too high? Is there enough cash? Is the earning power he originally liked still there? If nothing about the business has actually changed, and the stock only fell because the whole market panicked, then the drop can be exactly where the opportunity shows up. There's an important distinction buried in here: a falling price is not the same thing as a company getting worse.
Lynch liked to make the point with a simple example. If a stock was already absurdly overpriced, going from $60 to $50 doesn't necessarily make it cheap. But if a company was fairly valued around $40 and panic drags it down to $30, that's a completely different situation — for someone who actually understands the business, that's the stock they liked going on sale. What Lynch cared about was never "how much did it fall," but "why did it fall, and did the business actually get worse." That question matters far more than waiting for some perfect-looking low on a chart.
You don't need to understand a thousand companies — just the ones you own
This connects to another core piece of Lynch's philosophy: the average investor doesn't need to track thousands of companies at once. Instead of chasing whatever stock might double next, it's worth actually understanding the handful of businesses you're already in. Lynch's bar was high — if you genuinely believe in a company, you should be able to stand up and explain your reasoning in plain terms. That kind of understanding isn't knowing the latest headline about the company; it's knowing how it makes money, how much debt it carries, how much cash it holds, what's shifting in its industry, and what's actually supposed to drive its future earnings. Once you've done that homework, a falling price becomes something you can actually judge — is this "cheap," or is something "broken"?
Flip that around and look at how people actually invest today: a lot of time goes into hunting for the next stock that might go up tenfold, and almost none goes into truly understanding what's already sitting in the portfolio. On the way up, that gap doesn't show — prices keep rising, so every reason to hold looks correct. It's only once the market turns and prices start sliding that the real problem surfaces. Someone who thought they were investing in a company suddenly has no idea why it's falling, and starts refreshing the news every day just to reassure themselves it's still okay to hold. In the end, most people don't sell because they did the work and found the fundamentals had deteriorated — they sell because they couldn't stomach the drop. Looking back, what was missing was rarely a sharper signal for the bottom. It was ever really understanding what they'd bought in the first place.
How "just wait for the bottom" pushes the bottom further away
And this is exactly where "wait for the bottom" runs into trouble. Early in a decline, most people tell themselves to just wait a little longer. Down 10%, and it might fall another 20%. Down 20%, and maybe this is the start of a real crisis. Once everyone is genuinely scared, the fear shifts to whether this is only the halfway point. The market never sends a notice when the low is in — the bottom is only ever obvious in hindsight. To someone actually living through it, every price just looks like one that could still go lower. And to make it worse, once the market starts to recover, the same investor who was waiting now needs even more confirmation that the rally is real — and by the time they get it, the price has usually moved well past the bottom.
You don't have to guess the bottom — you just have to not need to
So the whole idea of "buying the bottom" can be reframed entirely: the goal was never to guess the exact low — it's to build a plan that doesn't require guessing it at all. Once an investor has done the homework and knows what they hold is something worth owning for the long run, investing on a schedule produces a very direct effect: buy some on the way up, keep buying through the chop, keep buying through the decline. The lower the price goes, the more shares the same dollar amount buys, and a stretch of decline naturally builds up a string of lower-cost positions. This is exactly the part of DCA that gets overlooked. People tend to think of it as "I can't judge the market, so I just buy on autopilot." Flip that around, though, and it's actually solving a problem nobody can solve: nobody can stand in the middle of a decline and know for certain this is the bottom. If a plan requires that answer before it can act, the waiting itself is what costs you the window that mattered most. Built the other way, with continuous buying from the start, a falling market stops being a moment that forces an "is this the bottom" verdict — it's just another stretch of the plan already in motion.
This doesn't mean buy every dip no matter what
None of this means every falling asset deserves more money without question. Lynch's real warning still holds: before a price looks cheap, check whether what you're buying has actually gone bad. If a company's earning power, balance sheet, or long-term competitive position has genuinely broken down, adding more just because the price fell a lot isn't buying the bottom — it's something else entirely. Continuing to invest only makes sense if what you're holding still fits the original long-term case. If there's extra cash on hand, it's reasonable to add more during a sharp decline as long as the fundamentals are intact — but that's a very different mindset from waiting to nail the exact low and betting it all at once.
Back to that 1997 interview
Back to the 1997 interview: what Lynch was really trying to tell investors wasn't whether the market would go up or down. He said plainly that he had no idea whether the next 1,000 points would be up or down, and that guessing short-term direction wasn't worth much effort. What actually mattered was whether corporate earnings would keep growing over the long run, and which companies' fundamentals held up even when prices didn't, during a sharp correction. Neither a high market nor a falling one calls for an emotional overreaction. What's actually required is knowing what you own, and having a method you can actually keep following.
The lowest point of a decline might last one day, or even a few hours. But a genuinely effective buying window during a decline can run for weeks, months, sometimes longer. If your approach keeps money flowing in throughout that whole stretch, missing the single lowest day doesn't mean you missed buying the bottom. What actually matters is staying able to keep following the plan through the exact stretch when the market is most afraid and prices are cheapest.
Seen this way, "buying the bottom" stops being some mysterious skill. It doesn't require a perfect forecasting tool, and it doesn't require nailing every turn. Pick assets you genuinely understand and are willing to hold for the long run, invest in a way you can actually sustain, don't chase sentiment on the way up, and don't stop out of fear on the way down. When the next real crash hits, you don't have to wait until everyone agrees "this is the bottom" before acting, because the real buying of the bottom was already happening, a little at a time, all the way down.
Turns out buying the bottom isn't hard at all. What's hard is that it's always been treated as something you can only do by guessing the exact low correctly.
The 1997 Charlie Rose interview, the Dow's run from roughly 4,000 to 8,300, and the Asian financial crisis context are drawn from public historical records; the quoted line is Lynch's own words. This article is educational and does not constitute investment advice.